 Kenal
For licensed lenders and moneylenders
Originate, disburse and collect loans, conventional or Islamic, with identity, documents and stamping built in.
Last updated
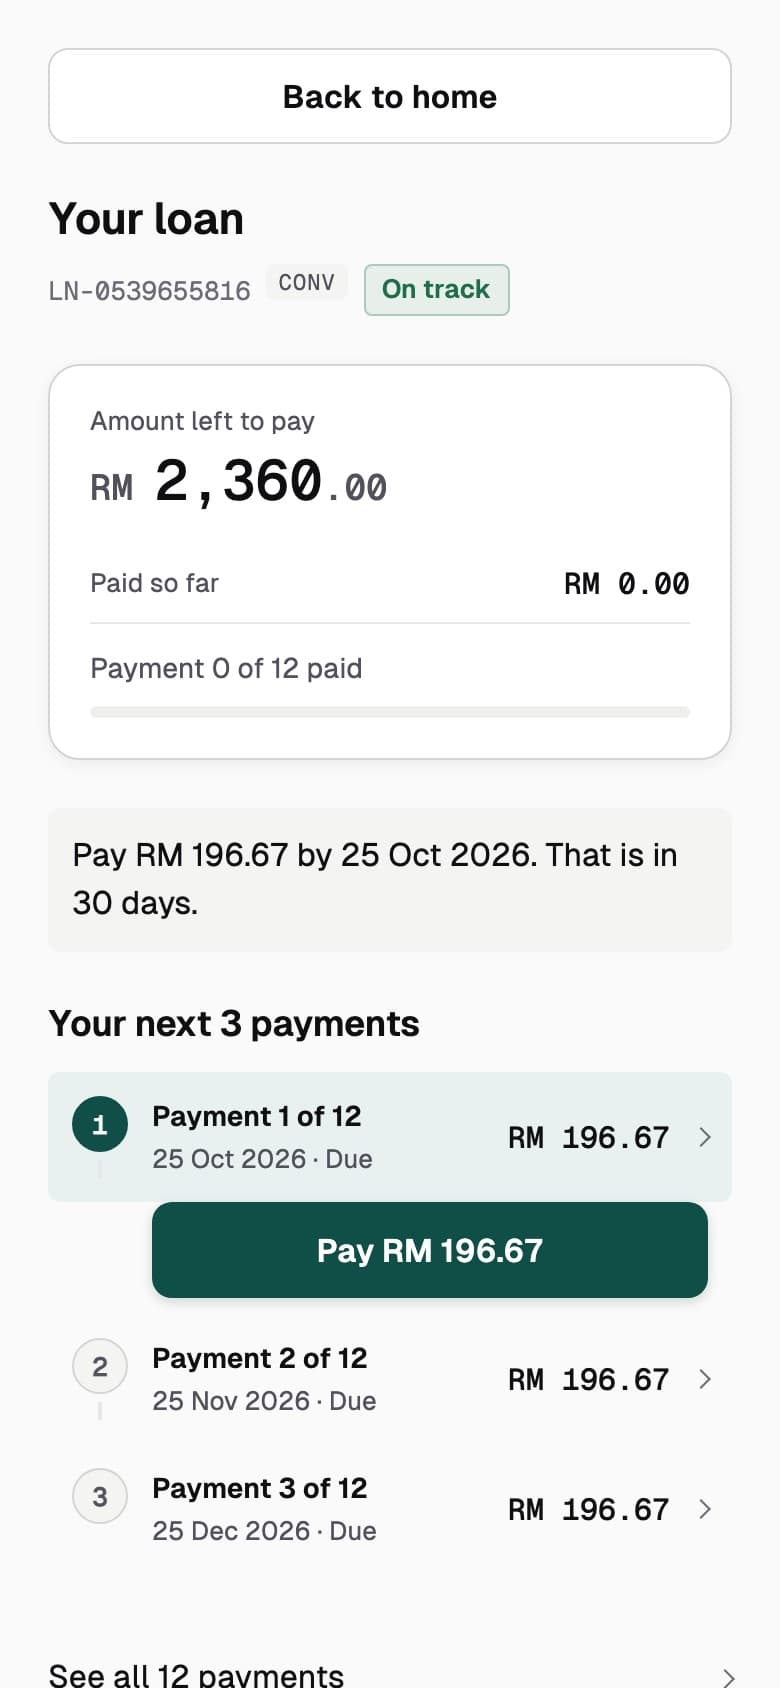
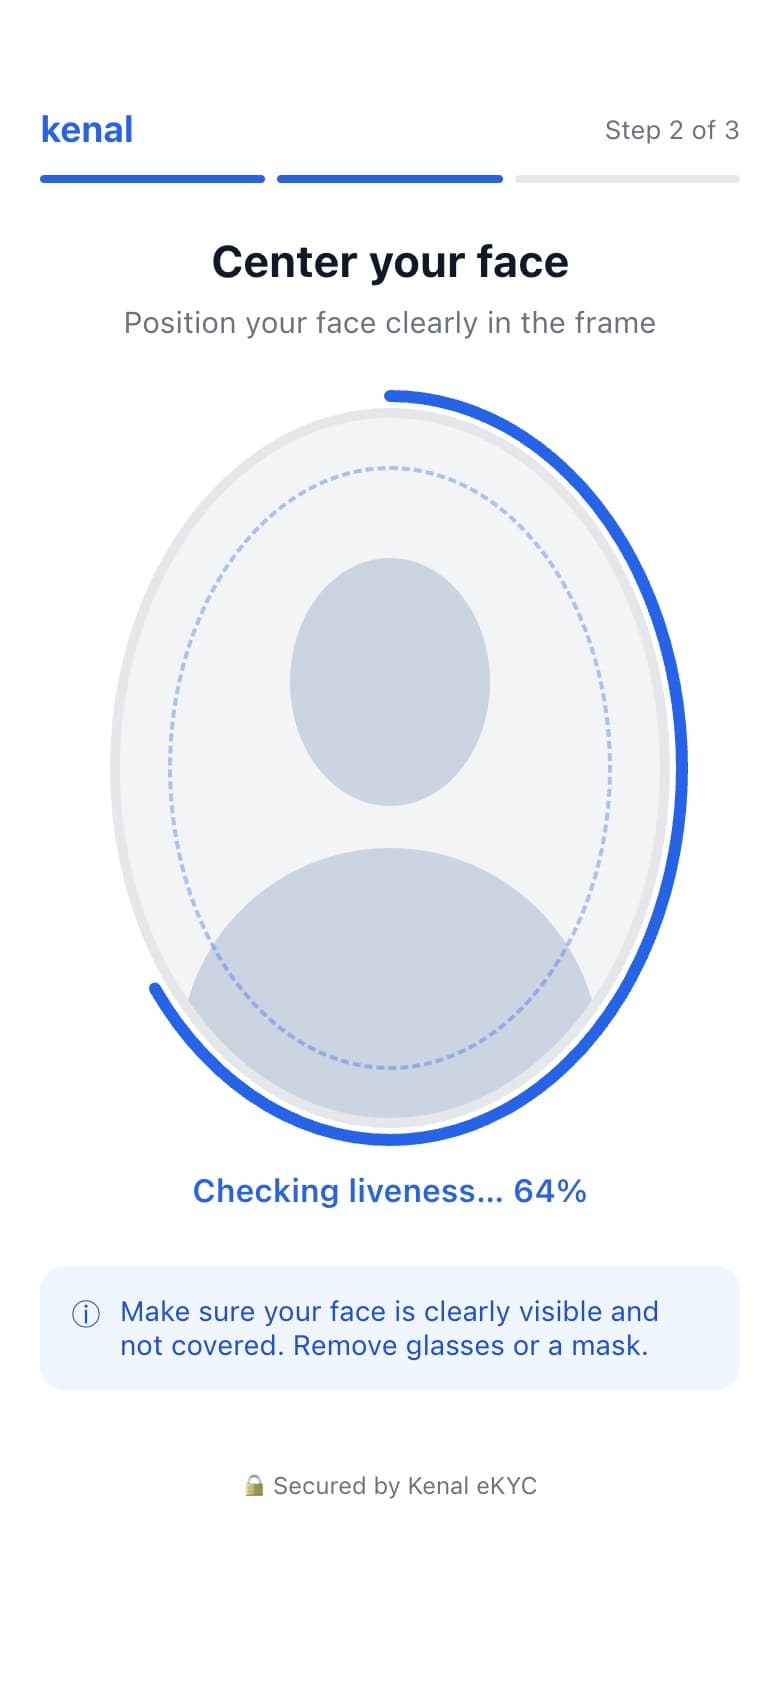
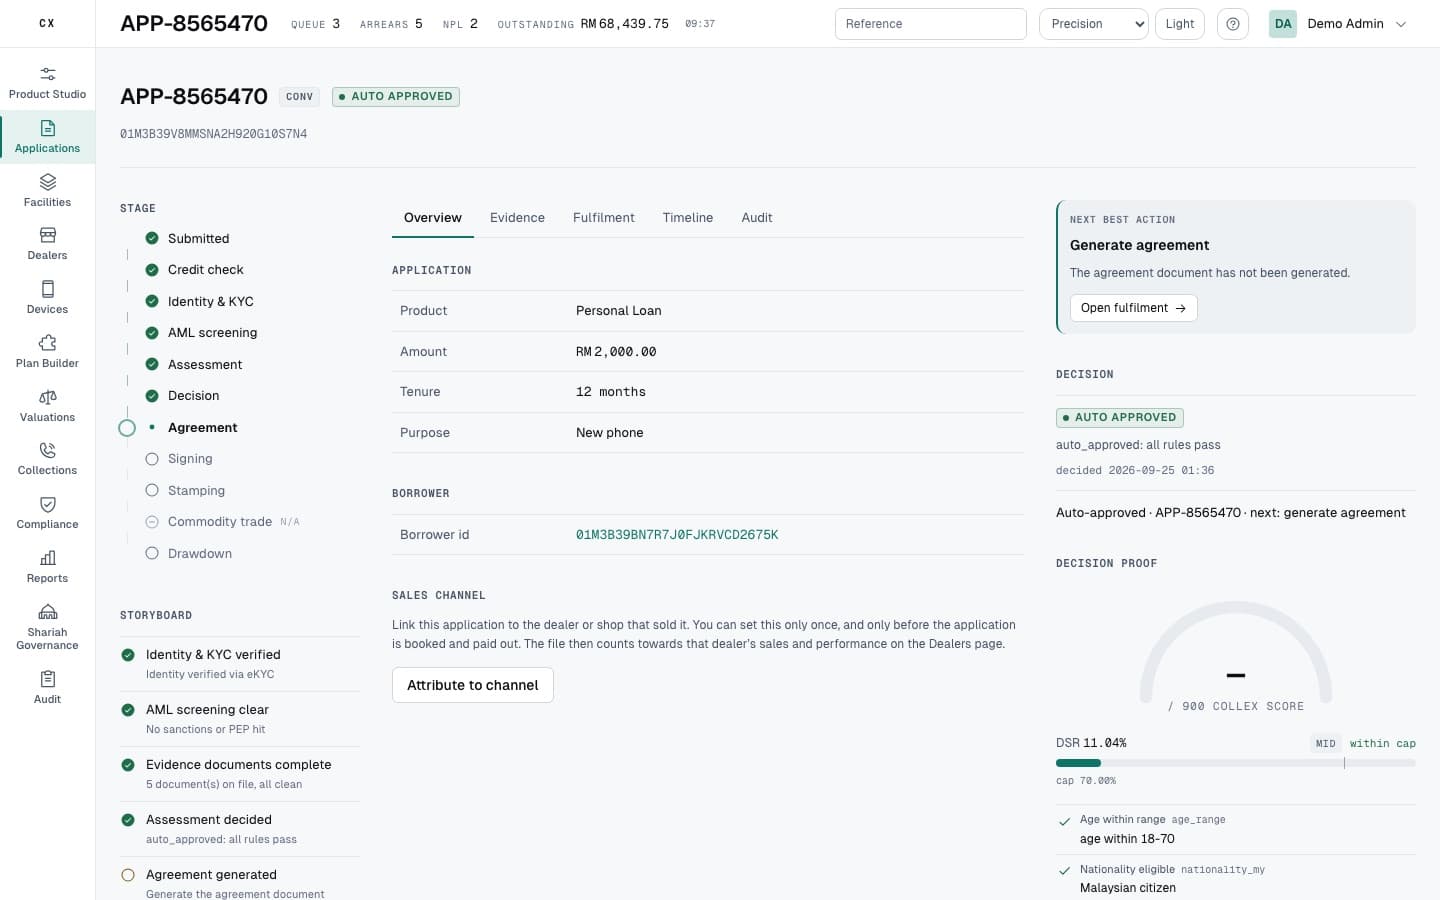
Kenal for lenders is a loan origination and management system with identity verification, bank statement analysis, signing and LHDN stamping built in, so licensed lenders and moneylenders can take a loan from application to repayment, conventional or Islamic, in one place.
What you can do with Kenal
- Originate and manage loans, conventional or IslamicFrom application to repayment in one system, including Tawarruq and Murabahah.Kenal Loan
- Verify every borrower remotelyMyKad or passport, liveness, face match and AML screening in one flow.Kenal eKYC
- Read bank statements and catch tamperingIncome and commitments from any Malaysian bank statement, in seconds.Kenal Document
- Sign agreements tied to a verified identitySignatures bound to the borrower verified at application and a one-time code.Kenal Sign
- Stamp loan agreements with LHDNDuty assessed, filed and the certificate returned to the loan record.Kenal Stamps
Example: a personal loan
A borrower applies on their phone and the loan moves from identity to stamped agreement without re-keying.
Step 1: Kenal eKYC
The borrower verifies their MyKad, passes liveness and face match, and is screened against AML, PEP and sanctions lists.
Step 2: Kenal Document
Their bank statements are structured in seconds, income is detected and tampering is flagged.
Step 3: Kenal Loan
The application is scored and decided, then disbursed and scheduled for repayment in the same system.
Step 4: Kenal Sign
The borrower signs the agreement, bound to the identity verified at the first step.
Step 5: Kenal Stamps
The agreement is assessed for duty, filed with LHDN and the stamp certificate is returned to the loan record.
One loan record holds the identity, the evidence, the decision, the signed agreement and its stamp certificate.
For KPKT-licensed moneylenders
Collex is the Malaysia edition of Kenal Loan for moneylenders licensed by KPKT, with the Moneylenders Act workflow and KPKT monthly portfolio returns produced from the same ledger. About Kenal Loan
Built for your regulator
Lending rules are specific about disclosure, agreements and records. We build the workflow around them.
- Moneylenders Act 1951 (KPKT)
- Agreement, disclosure and record-keeping steps built into the Collex workflow, with KPKT monthly portfolio returns from the ledger.
- Hire-Purchase Act 1967
- Hire-purchase modelled as its own product type, with the Act's terms and charges set per licence.
- Stamp Act 1949 (LHDN)
- Loan agreements assessed and stamped through LHDN self-assessment, with the certificate kept against each loan.
We describe what we build to. Approval of your programme rests with you and your regulator. Read more on security at Kenal.
Questions we hear
What is Collex?
Collex is the Malaysia edition of Kenal Loan for moneylenders licensed by KPKT. It runs the full loan lifecycle, from borrower verification and assessment through the agreement, disbursement, repayment and collection, and produces the KPKT monthly portfolio return from the same ledger. It uses the same engine as Kenal Loan, so a lender can add Islamic financing or new products later.
Can one system handle both conventional loans and Islamic financing?
Yes. Kenal Loan runs conventional loans and Islamic financing side by side, including Tawarruq and Murabahah structures. Each product is set up with its own terms, pricing and schedule, while origination, approval, disbursement, repayment and collection share one workflow and one ledger. Market packs cover Malaysia and Indonesia, so the same platform can serve both markets.
Do lenders have to stamp loan agreements with LHDN?
Most loan agreements in Malaysia attract stamp duty and must be stamped through LHDN. Kenal Stamps automates the job: it assesses the duty under self-assessment, files the agreement on the LHDN STAMPS portal and returns the stamp certificate to the loan record. Your team no longer keys agreements into the portal one by one, even at high volume.
Talk to our lending team
Tell us how you lend today. We will show you the loan journey live, from application to stamped agreement.